When should we claim Social Security?
We test claiming ages from 62 to 70 for both of you and show the lifetime difference in dollars.
Retirement income planning in Birmingham
We write your monthly retirement paycheck plan: when to claim Social Security, which account to draw from first, and what you'll owe in tax.
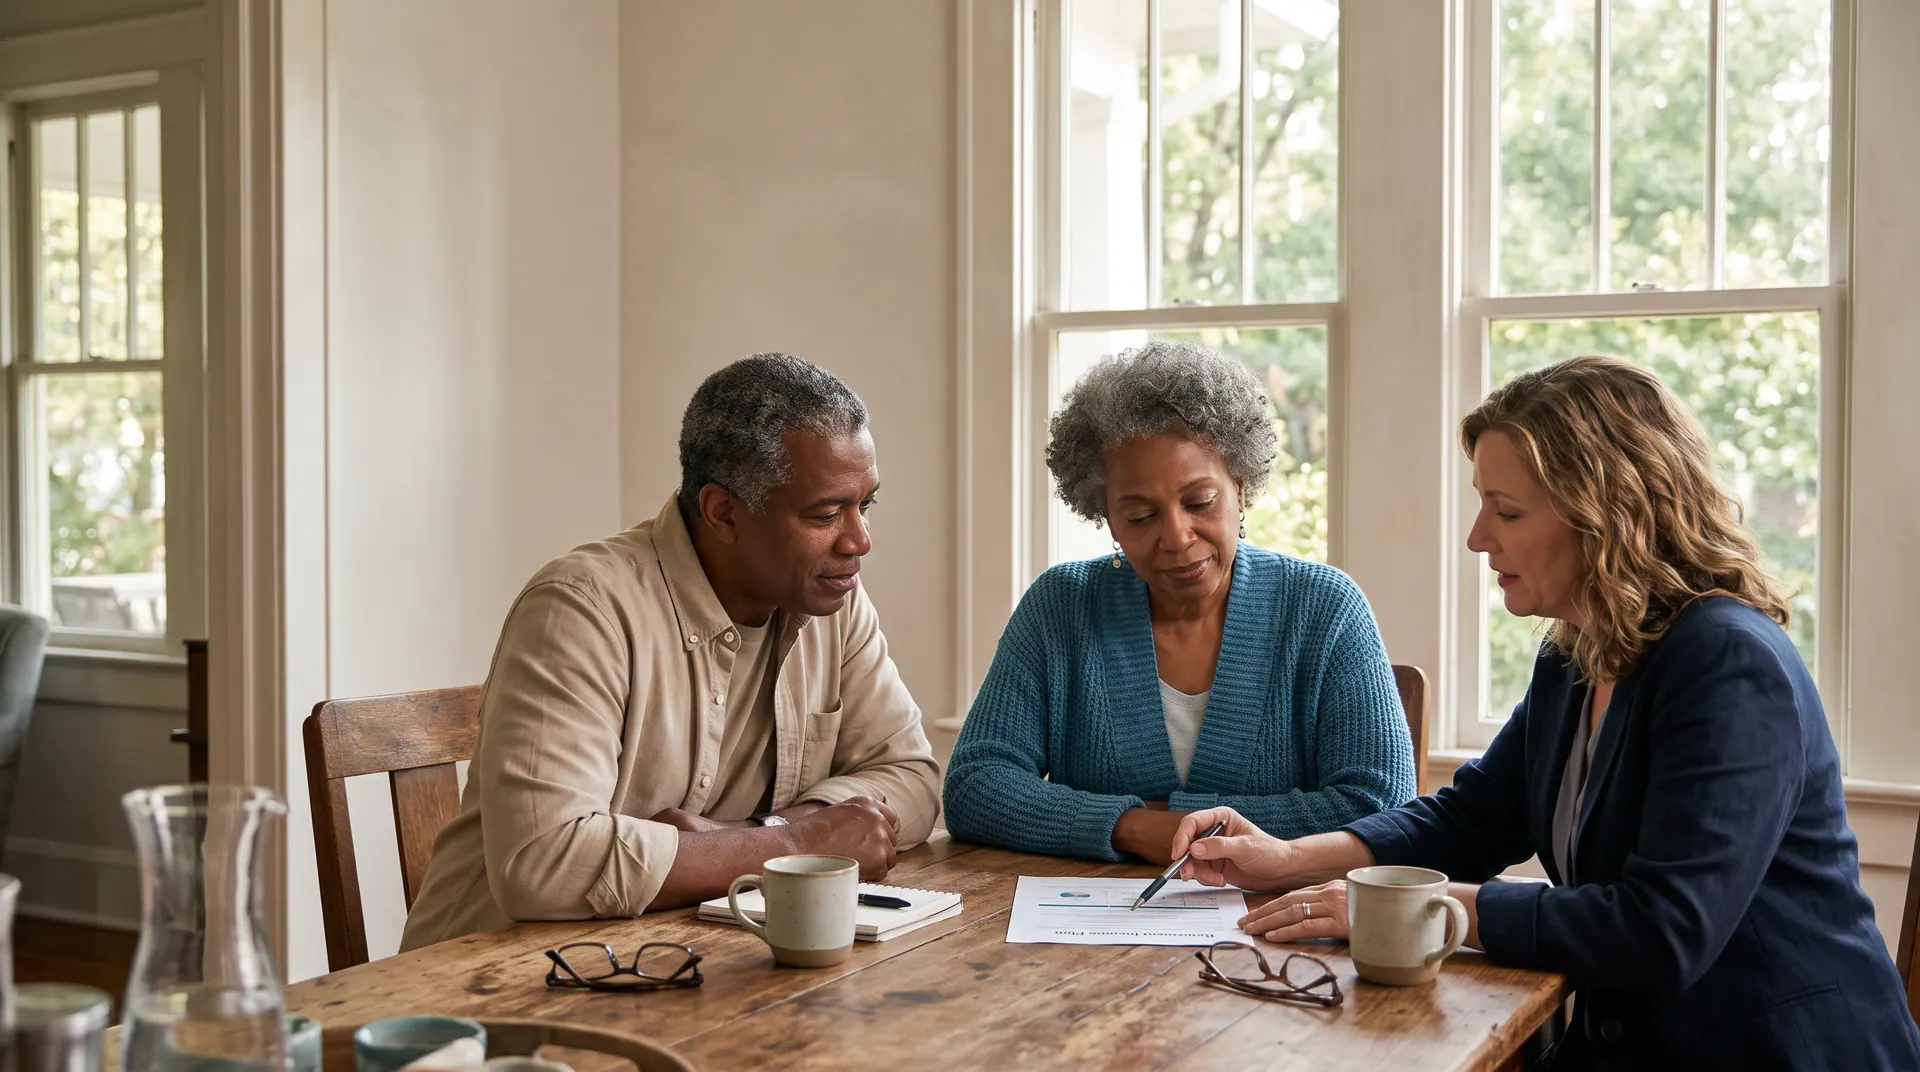
What your plan answers
You saved for 30 years. Turning savings into a steady paycheck takes a different kind of plan, and it should fit on paper you can read.
We test claiming ages from 62 to 70 for both of you and show the lifetime difference in dollars.
Taxable, IRA or Roth. The order can change your tax bill by thousands a year, so we map it out.
We compare the offer side by side for TRS, city, utility and steel company pensions.
The years between retiring and claiming are often your lowest tax years. We size each conversion.
We budget for coverage until Medicare starts and keep income low enough to protect subsidies.
We stress-test the plan against a bad first decade in the markets and show what we would adjust.
The paycheck plan
Your plan ends with one chart and one page of steps. Pin it to the fridge. Hand it to your kids. Bring it to your CPA.
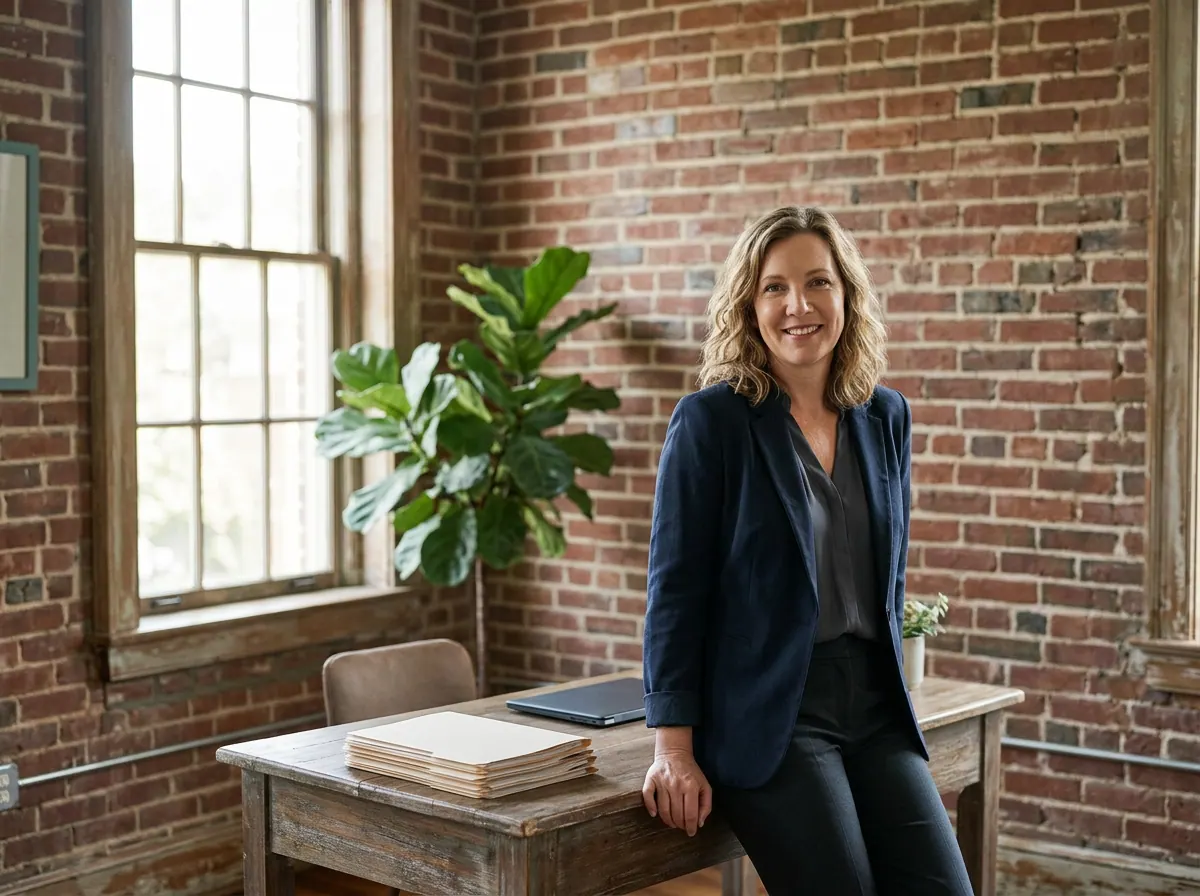
Who you'll work with
I spent 11 years at a big brokerage watching people get great advice on saving and almost none on spending. In 2012 I opened Shades Creek to do the second part well. I work with about 90 households, so I answer my own phone.
Claire Whitfield, founder, Shades Creek Income Planning
How it works
Most plans are finished within four weeks of our first conversation.
Tell us when you hope to stop working and what worries you. We'll tell you if a plan is worth the fee.
Week 1, by phone or in HomewoodSend statements, pension letters and your Social Security record. We do the math and draft your plan.
Weeks 2 and 3A two-hour meeting at your table or ours. You leave with the chart, the steps and the transfers set up.
Week 4Fees
We never charge a percentage of your savings, and we don't earn commissions on anything.
Already have a plan from someone else? We check it for gaps and send a written review.
The full written plan, built on your own numbers and set up so the deposits start.
After your plan, we keep it current as taxes, markets and life change. Cancel anytime.
Your quote is in writing before any work begins. If we can't help, the consultation costs nothing.
Reviews
"I retired from the steel plant and had to pick a lump sum or a pension by Friday. Claire ran both that week. We took the monthly check and I sleep fine."
"We were going to claim Social Security at 62. Waiting until 70 for my husband adds about $1,400 a month for whichever of us outlives the other. That one page was worth the fee."
"The first deposit hit our checking on the 3rd, just like the plan said. For the first time since I retired, money feels boring, in a good way."
Questions
Something else on your mind? Call and Claire will pick up or call you back the same day.
No. Your accounts stay where they are. We tell you what to set up and walk you through it, or we can join the call with your bank.
Five years before you stop working is ideal. Many choices, like Roth conversions and claiming ages, work best when there is time to plan them.
No. We don't sell any products. If an annuity truly fits your plan, we'll explain why and you can buy it anywhere you like.
No one honestly can. We show how the plan holds up in good and bad markets, and what we'd change if returns come in low.